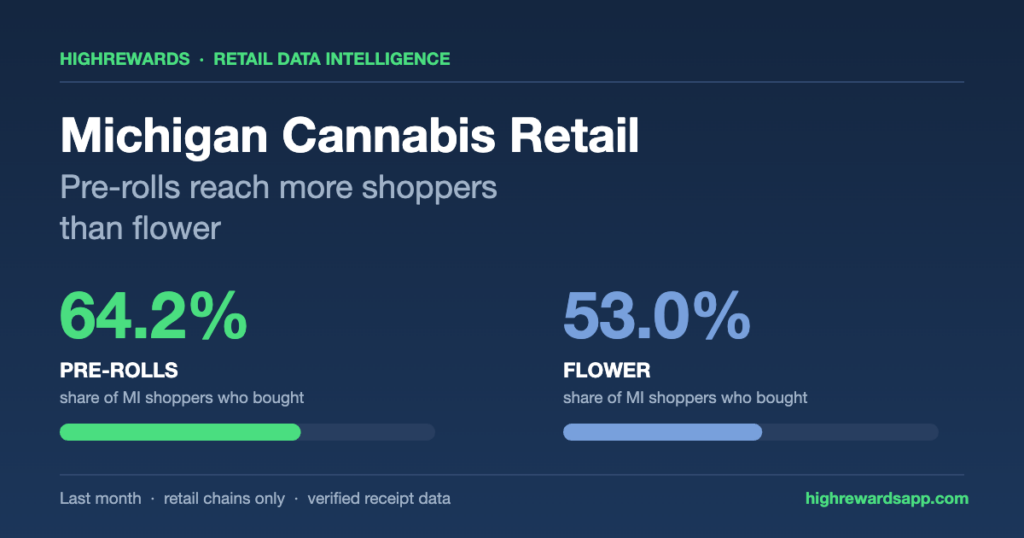
Last month, 64.2% of Michigan cannabis shoppers in the HighRewards receipt network bought at least one pre-roll. Only 53.0% bought flower.
That is the widest reach gap we have measured in a mature Michigan market, and it flips the usual assumption about what a dispensary’s core category actually is. Flower still earns more. Pre-rolls simply touch more people.
Reach and revenue are two different rankings
Rank Michigan categories by the share of shoppers who bought them and you get one order. Rank them by share of spend and you get another.
- Shopper reach: pre-rolls 64.2%, flower 53.0%, vapes 41.0%, edibles 33.0%, concentrates 23.1%
- Share of spend: flower 37.1%, pre-rolls 31.8%, vapes 13.6%, concentrates 10.6%, edibles 5.7%
- Share of units bought: pre-rolls 49.6%, flower 15.5%, edibles 13.6%, vapes 13.0%, concentrates 6.4%
Roughly one in every two items leaving a Michigan counter is a pre-roll, but pre-rolls account for under a third of the money. The average pre-roll unit prices about three quarters below the average flower unit, so volume does most of the work and margin does very little of it.
We saw a milder version of this pattern across the whole network in our pre-roll analysis. Michigan runs well ahead of it.
Michigan is a frequency market with a basket problem
Compared with the retail network average last month, Michigan shoppers behave like this:
- Visit frequency runs about 9.7% below the network average
- Average basket runs about 18.5% below the network average
- Spend per customer lands about 27.6% below the network average
- Repeat rate is 56.1% against 60.0% for the network
- Loyalty rate, meaning three or more visits, is 38.2% against 41.0%
Frequency is close. Basket size is not. Michigan’s shortfall is almost entirely a basket problem, and the category mix explains most of it.
The state market also contracted 5.8% month on month, slightly steeper than the 5.2% network decline.
No brand owns Michigan
The top brand in the state holds 13.3% of tracked spend. The top ten brands together hold roughly 32%, which leaves about two thirds of the market outside the leaderboard entirely.
For a brand, that is opportunity. For a retailer, it means shelf loyalty is weak and the basket is being decided in the store, not before the shopper walks in. It also explains why brand-side reach is so hard to buy here: the usual channels are closed, which is the subject of our guide to cannabis advertising.
What the strongest chains do differently
The leading Michigan chain holds about 24.9% of tracked state retail revenue, and the top three together hold roughly 45%. Concentration at the top is real, which we covered in the Michigan wallet share breakdown.
The more useful signal sits just below the leaders. King of Budz posts the highest repeat rate in the state’s top five at 66.7%, and its spend per customer runs about 27% above the Michigan average. It is not winning on footfall. It is winning on what happens after the second visit.
What to do with this
- Treat the pre-roll as an acquisition product, not a margin product. It reaches more Michigan shoppers than anything else on the shelf, which makes it the best attach point you have.
- Build the attach, not the discount. A pre-roll basket that adds one mid-price item closes most of the 18.5% basket gap on its own.
- Measure reach separately from revenue. A category ranked fifth by spend can still be the one your shoppers actually see you for.
- Own the third visit. Michigan loses more shoppers between visit two and visit three than the network does, and that is where the basket compounding starts.
How we measured this
Figures come from verified receipts uploaded by HighRewards users in Michigan last calendar month, filtered to retail chains only. All figures are aggregated. We publish shares, rates and comparisons rather than totals, and we never publish anything at the level of an individual shopper.
FAQ
Do pre-rolls really outsell flower in Michigan?
By units and by shopper reach, yes. Pre-rolls made up 49.6% of units bought and reached 64.2% of shoppers. By spend, flower still leads with 37.1% against 31.8% for pre-rolls.
Why is the Michigan basket smaller than the network average?
Mostly category mix and price compression. Half of all units bought are low-priced pre-rolls, which pulls the average basket about 18.5% below the retail network average even though visit frequency is only about 9.7% lower.
Which brand leads Michigan?
No brand holds a commanding position. The top brand accounts for 13.3% of tracked spend and the top ten together hold roughly a third of the market.
Is the Michigan market growing?
Not last month. Tracked Michigan retail spend fell 5.8% month on month, a little steeper than the 5.2% decline across the wider retail network.
Want market reports like this for your state? HighRewards builds retail intelligence from verified cannabis receipts across every legal market. If you run a dispensary chain or a brand and want to see where your wallet share actually sits, get in touch.